Apartment Building Financing in San Jose: A $1,050,000 Acquisition Loan Closed in 6 Days
LTV: 50%
In short
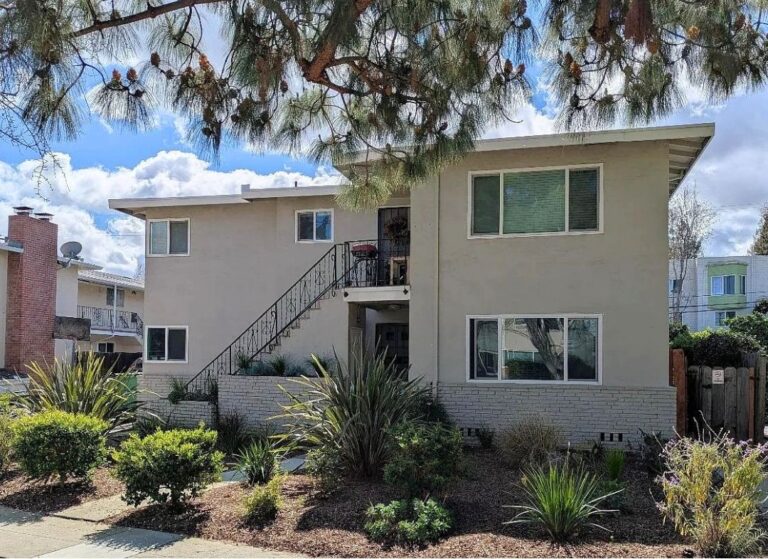
Rubicon Mortgage Fund, LLC closed a $1,050,000 acquisition loan on a fully occupied 5-unit apartment building in San Jose, California, in 6 days. The buyer was under contract and in underwriting with a bank when credit issues prevented the loan from moving forward about two weeks before the scheduled closing. With substantial equity in the deal, a well-located, turnkey property, and a responsive mortgage broker, RMF stepped in and closed the acquisition on time.
The property: a turnkey 5-unit building in San Jose
The property is a 5-unit apartment building of approximately 5,200 square feet, with large units averaging roughly 1,000 square feet each and seven off-street parking spaces in the rear. It sits in an established San Jose neighborhood surrounded by other multifamily buildings, a location with steady rental demand.
The building was fully occupied at acquisition and needed no renovation. Loan proceeds were used for the purchase only.
The borrower: an experienced San Jose investor
The buyer is an experienced local investor who owns several other properties in San Jose along with two San Jose restaurants. She is growing her real estate portfolio as part of a longer-term plan to shift her focus from operating businesses to owning income-producing real estate.
The challenge: bank financing stalled two weeks before closing
The buyer was under contract and working through underwriting with a bank. Bank underwriting typically weighs the borrower’s personal profile heavily, including credit history, financial statements, and other factors, alongside the property itself. In this case, credit issues on the borrower’s report kept the loan from being approved, and the financing fell through roughly two weeks before the scheduled close of escrow.
The banker working on the file knew the property and the buyer’s equity position were strong, and introduced the buyer’s mortgage broker to Rubicon Mortgage Fund, LLC.
The solution: asset-based apartment building financing
As an asset-based lender, Rubicon Mortgage Fund, LLC underwrites primarily to the real estate. The fundamentals here were clear:
- Strong real estate: a well-located, fully occupied building with no deferred work required
- Significant borrower equity: the buyer brought a substantial cash down payment to the purchase
- An experienced owner: a local investor with an existing portfolio in the same market
Those factors gave RMF a sound basis for the loan, and the borrower’s credit history did not stand in the way of the transaction.
How the loan closed in 6 days
Because the buyer had already been through a bank underwriting process, most of the documentation was assembled and ready. The mortgage broker, working with RMF for the first time, delivered every item RMF requested promptly and worked closely with RMF’s in-house loan processing team through closing.
With underwriting, legal, and servicing all handled internally, RMF was able to review the file, approve the loan, and close in 6 days, keeping the buyer’s purchase on its original timeline.
A timeline like this depends on the parties involved. When the borrower and broker are responsive and the documentation is in order, Rubicon Mortgage Fund, LLC can move as quickly as the deal allows.
The exit strategy
RMF provided a 12-month loan. During the term, the borrower plans to address the items affecting her credit and position the property for long-term financing, while the fully occupied building continues to generate income.
Why this deal worked
- The real estate carried the loan: good location, full occupancy, and a turnkey building
- Meaningful equity: the buyer’s substantial cash investment provided a strong equity cushion for the loan.
- Prepared, responsive partners: a broker who delivered documents on time and a file that was largely assembled
- In-house execution: underwriting, legal, and servicing handled internally from application to funding
Frequently asked questions
What is apartment building financing?
Apartment building financing is a loan used to purchase or refinance a residential property with five or more units. Because buildings with five or more units are considered commercial real estate, they are typically financed with commercial loans rather than residential mortgages.
Can you get an apartment building loan with credit issues?
Yes. Asset-based private lenders such as Rubicon Mortgage Fund, LLC underwrite primarily to the property’s value, location, and income, as well as the borrower’s equity in the deal. Credit is reviewed, but credit issues do not automatically prevent a loan when the real estate and equity are strong.
How fast can a private lender close an apartment building loan?
Timing depends on the transaction and how quickly documentation is provided. In this San Jose acquisition, Rubicon Mortgage Fund, LLC closed in 6 days because the property was straightforward and the borrower and broker supplied everything requested promptly.
What happens if bank financing falls through before closing?
If a bank loan falls through during escrow, a buyer may be able to keep the purchase on track by moving to a private lender that can underwrite and close within the remaining contract timeline. Having property information, financial documents, and a responsive broker helps the new lender move quickly.
What loan terms does Rubicon Mortgage Fund, LLC offer for apartment buildings?
Rubicon Mortgage Fund, LLC offers loans from $500K to $15M with terms from 6 to 24 months, fixed interest-only payments starting at 8.5%, and fees starting at 1.0%. RMF lends on multifamily properties throughout California.
Work with Rubicon Mortgage Fund, LLC
Rubicon Mortgage Fund, LLC is a Lafayette, California-based private money lender providing short-term, asset-based business purpose real estate financing. With in-house underwriting, servicing, and legal, RMF works directly with borrowers, brokers, and bankers on multifamily acquisitions and other commercial and investment real estate transactions across California.
Have an apartment building purchase that needs financing? Contact our team to discuss your scenario.
To see more funded deals, click here!
To keep up with us, click here!