Blanket Loan: How One $9,000,000 Refinance Replaced 33 Maturing Loans on a San Rafael Condominium Portfolio
LTV: 66%
In short
A family office owned 33 of the 36 units in a San Rafael condominium complex, each financed with its own first loan. When those loans came due ahead of the borrower’s plans, Rubicon Mortgage Fund, LLC replaced all 33 with a single $9,000,000 blanket loan and cleared the units from a second-position line of credit. With one first deed of trust, the family office is positioned for long-term stability as it arranges for traditional financing.
Loan highlights
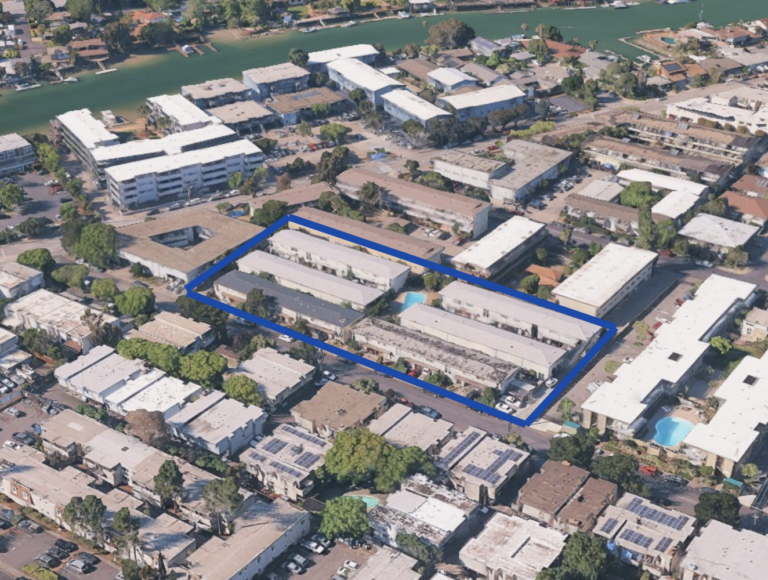
This $9,000,000 blanket loan is secured by 33 occupied, cash-flowing condominium units totaling approximately 58,760 square feet of building area on 1.5 acres in San Rafael, California. Proceeds refinanced 33 maturing first deeds of trust. The term is 12 months, the planned exit is a conventional refinance, and the loan was referred by a mortgage broker.
The problem with owning a building one unit at a time
Condominiums are legally separate parcels. Each unit has its own title, its own tax bill, and usually its own loan. For an investor who buys units over time, financing them individually is the natural path, and it works well while the loans are performing and the maturities are spread out.
The tradeoff shows up later. An owner holding dozens of units in one complex ends up managing dozens of notes, each with its own lender terms, payment schedule, and maturity date. When those maturities line up, the owner has to refinance the whole group at once, and a conventional refinance of 33 separate parcels is a long, document-heavy process.
That is where this family office found itself.
The property: a near-whole complex in Marin County's largest city
San Rafael is the county seat and largest city in Marin County, about 17 miles north of San Francisco along U.S. Highway 101, with a stop on the SMART commuter rail line. Marin County’s limited supply of new housing has historically supported consistent rental demand, and the complex sits in a well-located part of the city.
The borrower owns 33 of the 36 units on the 1.5-acre site. With nearly the entire complex under one owner and every one of its units leased, the property operates much like an apartment building: one operator, one rental program, and a combined income stream. All 33 units were occupied at closing.
The borrower: a family office with a Western U.S. portfolio
The borrower is a family office that owns real estate across the Western United States. Its principals are seasoned operators who have managed this complex and other income properties for years. The issue was never the asset or the operator. It was the calendar.
The challenge: two layers of debt on 33 parcels
First position: 33 individual first deeds of trust, one on each unit, all reaching maturity on a timeline the family office had not anticipated.
Second position: a line of credit secured by all 33 units, plus other properties in the borrower’s portfolio that were not part of this complex.
Any new lender stepping into first position needed both layers cleared from the 33 units: every first loan paid off, and the line of credit’s lien released from each condominium. With the maturities approaching, the borrower needed a lender able to treat the 33 units as a single asset and work through a closing with that many moving parts.
The structure: one loan, 33 parcels
A blanket loan is a single loan secured by more than one property. Here, one $9,000,000 note replaced 33 separate ones, and one deed of trust was recorded across all 33 parcels.
Closing the transaction meant coordinating four pieces at once:
- 33 payoffs. Payoff demands from each existing first-position lender, verified and funded at closing.
- Lien release from the line of credit. The second-position lien was released from all 33 units so the new loan could take first position.
- One blanket deed of trust. A single new first-position lien recorded against all 33 parcels.
- Title across 33 parcels. Title review and lender’s title insurance on every unit, so each condominium was confirmed clear before funding.
Because underwriting, legal, and servicing all sit in-house at Rubicon Mortgage Fund, LLC, one team handled the payoffs, release documents, and title work from term sheet through funding. The mortgage broker stayed closely involved throughout, which matters on a file with this many parties.
How we underwrote it
As an asset-based lender, we looked at the 33 units the way the market does: as one income-producing property. The underwriting focused on the location, the rent roll across all 33 units, full occupancy, and the condition of the complex.
The borrower’s experience mattered too. A family office that has operated this property for years, with a broader portfolio across the West, brings the kind of track record that supports a loan of this size.
The result was a single loan sized to the portfolio as a whole, rather than 33 small loans each weighed on its own.
The exit: a long-term DSCR refinance
The family office plans to refinance into conventional financing, most likely a DSCR loan. DSCR (debt service coverage ratio) lending is underwritten mainly to a property’s rental income relative to its debt payments, which suits a fully occupied, cash-flowing portfolio.
The blanket loan gives the borrower two things for that next step: time to arrange permanent financing without a maturity deadline pressing on 33 notes, and a cleaner capital stack to present to the next lender.
What condo portfolio owners can take from this deal
Track maturities across the portfolio, not loan by loan. When units are financed individually, maturities can cluster without anyone flagging it. A single schedule of every note and its due date shows the problem early.
Know which liens touch which parcels. Lines of credit and other blanket liens often reach across several properties. Before a refinance, map every lien so you know which releases the new lender will need.
Start refinance planning well ahead of maturity. A multi-parcel refinance involves more title work, more payoff demands, and more coordination than a single-property loan. Giving it extra lead time keeps options open.
Consider whether a near-whole complex should be financed as one asset. When one owner controls most of a building and runs it as a rental, a blanket loan can reflect how the property actually operates.
Frequently asked questions
What is a blanket loan?
A blanket loan, also called a blanket mortgage, is a single loan secured by two or more properties. Investors use it to finance or refinance a group of properties under one set of terms and one maturity date instead of managing a separate loan on each.
Can you get a blanket loan on condominium units?
Yes. Because each condominium is a separate legal parcel, a blanket loan can be recorded against multiple units in the same complex. This is common when one owner holds many units and operates them as rentals.
What is a release clause in a blanket loan?
A release clause lets the borrower remove an individual property from the loan’s collateral, typically by paying down a set amount, so that property can be sold or refinanced on its own. Terms vary by lender and are negotiated when the loan is structured.
What happens to a line of credit secured by a property that is refinanced?
If a line of credit is secured by several properties, the line holder generally must release its lien on any property being refinanced before a new lender can take first position. The line can remain in place on the borrower’s other properties.
Is a blanket loan the same as a cross collateral loan?
The terms overlap. Both describe a loan secured by more than one property. “Blanket loan” is often used when a portfolio of similar properties is financed together, while “cross collateral loan” often describes pledging additional properties to support financing on a primary one.
What loan terms does Rubicon Mortgage Fund, LLC offer?
Rubicon Mortgage Fund, LLC offers loans from $500K to $15M with terms from 6 to 24 months, fixed interest-only payments starting at 8.5%, and fees starting at 1.0%.
Work with Rubicon Mortgage Fund, LLC
Rubicon Mortgage Fund, LLC is a Lafayette, California-based private money lender providing short-term, asset-based commercial real estate financing. With underwriting, servicing, and legal in-house, we work with borrowers, brokers, and family offices on multi-property transactions like this one.
Have a scenario with a firm timeline that needs certainty of execution? Contact our team or call (925) 283-8919 to talk it through.
To see more funded deals, click here!
To keep up with us, click here!