Rubicon Mortgage Fund writes mobile home park loans across California, funding parks that are not yet stabilised and business plans a bank will only finance after they have already worked.
Why Mobile Home Park Loans Are Hard to Get
Mobile home parks are one of the few asset classes where the business plan is usually obvious and the financing usually is not. Below-market rents, deferred infrastructure, and a seller who has run the park casually for twenty years. The upside is visible from the road. The current cash flow will not support a conventional loan.
Agency lenders want stabilised income
A value-add park does not have stabilised income yet. That is the entire investment thesis. Agency and bank underwriting sizes the loan against trailing performance, which is precisely the number the buyer intends to change.
The configuration puts most lenders off
Park-owned homes, RV spaces, private water and septic, a mixed configuration, a caretaker residence on site. Each of these is normal in California parks and each one narrows the list of lenders willing to look.
Small parks fall below agency minimums
A great many California parks are simply too small for agency programmes. The asset can be excellent and the loan still be too small to be worth an institution’s process.
A Recent Mobile Home Park Loan
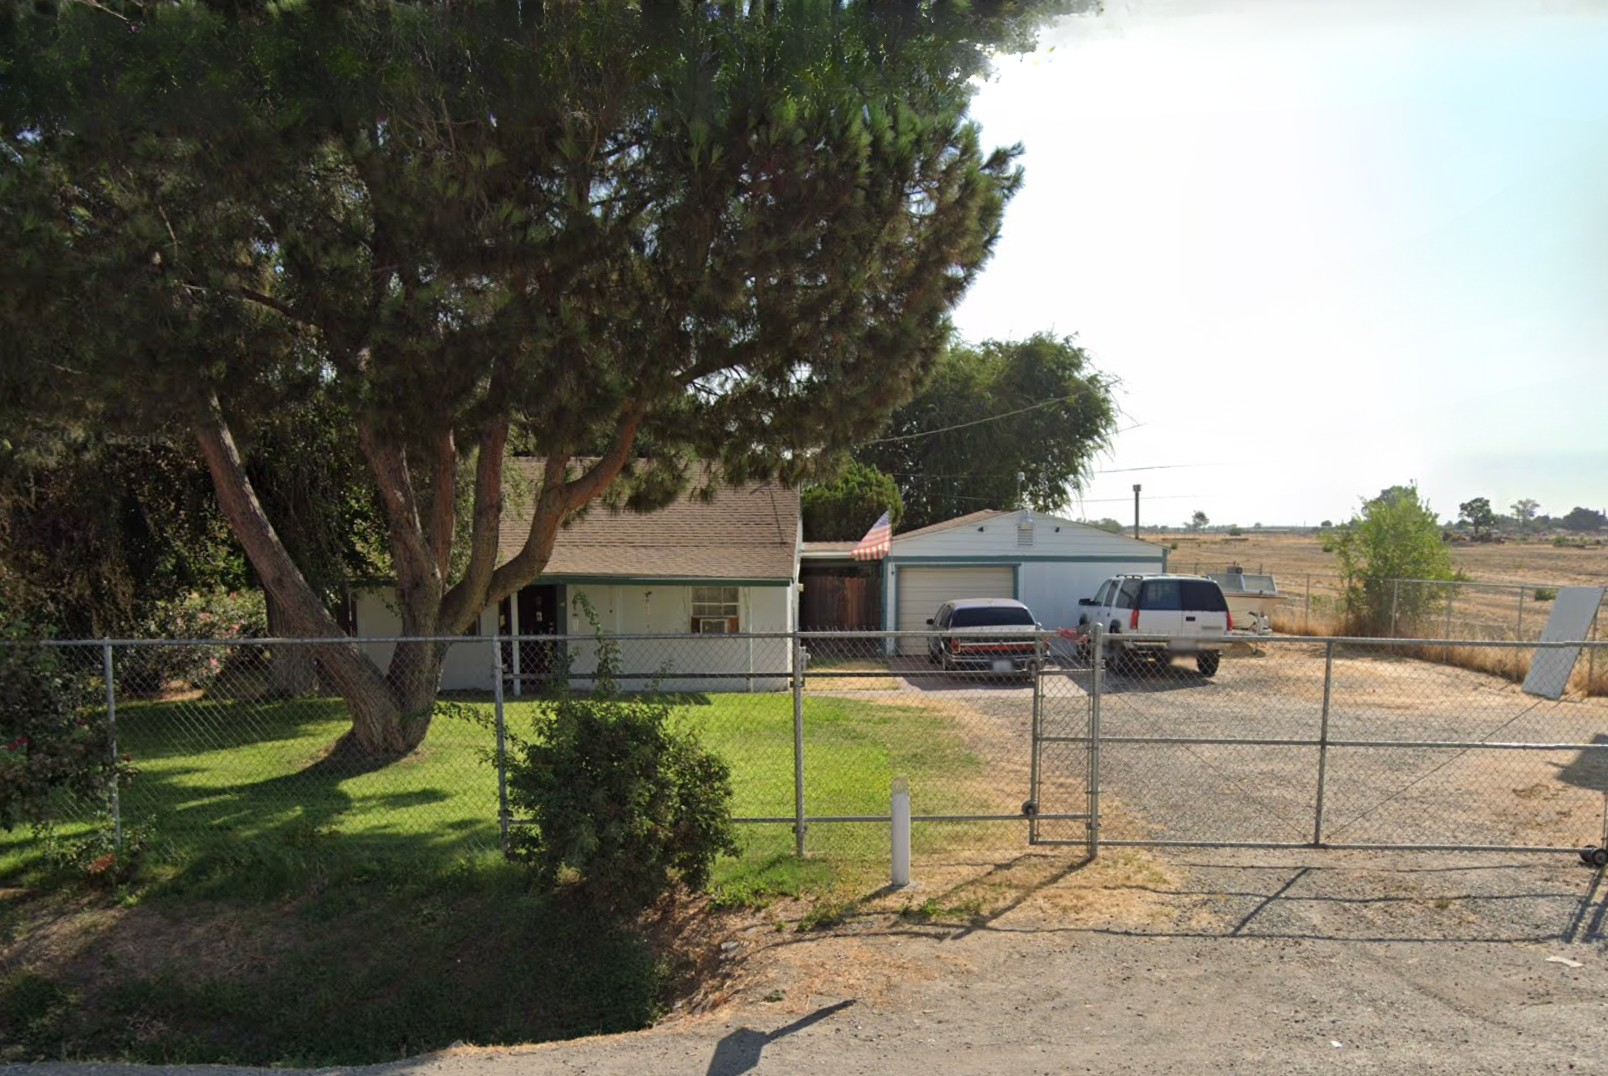
Rubicon funded a $750,000 acquisition in Oakhurst, in the Sierra Nevada foothills near Yosemite and Bass Lake. The park sits on 3.7 acres with 18 mobile home spaces, 11 RV spaces and a three-bedroom single-family residence.
The borrower had a clear value-add plan: upgrade the infrastructure and bring rents to market. Initial cash flow was insufficient for conventional financing, which is what made private capital the right tool rather than a fallback. The loan was cross-collateralized against a rental property the borrower owned in Stockton — a structure most conventional lenders will not accommodate — and closed in 30 days.
More closed transactions are listed on our funded loans page.
What We Look At
- Space count and occupancy, and the gap between current and market rents
- Infrastructure condition, particularly private water and septic systems, which is where the real capital risk sits
- Permitted use and zoning, and whether the permitted space count matches what is on the ground
- The improvement plan and what it actually costs
- The exit once the park is stabilised
Someone from Rubicon walks the park before we lend. For this asset class that means looking at the spaces and the utilities, not reading a rent roll. Full parameters are on our borrowers and lending criteria page.
What We Finance
Land-lease communities, all-ages and 55-plus, land-only parks and parks with park-owned homes, mixed mobile home and RV configurations, and small parks below agency minimums. Acquisitions, refinances, cash-out for capital improvements, and partner or family buyouts.
Mobile Home Park Loans: FAQs
Will you lend on a park that is not stabilised?
Yes. Under-occupied and under-rented parks are a normal part of what we see. We underwrite the property and the plan rather than trailing income.
Do park-owned homes cause a problem?
No. We are lending against the real estate; park-owned homes are part of the picture rather than a disqualifier.
What about private water and septic?
Common in California parks and not disqualifying, but it is the first thing we look at. Tell us the condition and any outstanding notices at the start.
Is there a minimum park size?
Our lending is sized by loan amount rather than space count, so small parks that fall below agency minimums are workable. See our lending criteria for the range.
Can I cross-collateralize another property?
Yes, and on park deals it is frequently what makes the numbers work. The Oakhurst loan was structured that way.
Do you require an appraisal or a credit check?
Neither. Someone from Rubicon inspects the park in person instead.
How fast can you close?
Most borrowers have preliminary terms within 24 hours. The Oakhurst acquisition closed in 30 days.
Are mobile home park loans regulated in California?
Yes. Rubicon lending is made or arranged pursuant to California Financing Law and overseen by the California Department of Financial Protection and Innovation. All loans are business purpose and secured in 1st position.